Flood insurance · Harris County
Flood insurance for your Houston home, explained and quoted by a local agent.
Home and renters insurance don't pay for rising water, and a new flood policy usually takes 30 days to start. Ricardo Barcelo checks your address, your lender's requirement and your current coverage, then quotes flood for the building, your belongings, or both.
Rather type? Request a flood quote
- 4.9 on Google, 265 reviews
- No charge to review your coverage
- English or Spanish · hablamos español
- Mon–Thu 9–6, Fri 9–5
Already a customer with a claim or billing question? Go to customer service.
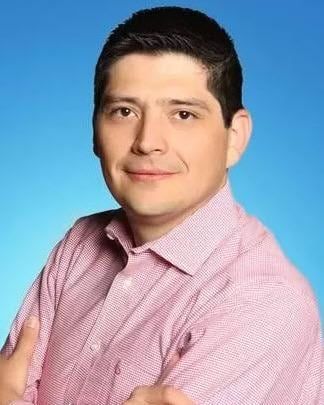
Ricardo Barcelo
Allstate exclusive agent, Barcelo & Associates Insurance, Houston Heights
Key facts
-
30 days
the usual wait before a new flood policy takes effect. There's no wait when it's bought with a mortgage closing or refinance.
-
More than half
of the homes Hurricane Harvey flooded were outside designated flood zones.
-
47.6%
of Harris County flood-claim dollars went to properties outside the high-risk zone, in our analysis of 170,843 FEMA claim records.
Source: Our ZIP-by-ZIP analysis
Why flood is its own policy
Who pays depends on where the water came from.
Insurers sort water damage by its source. That one detail decides whether a claim goes to your homeowners policy or a flood policy, so it's worth knowing before a storm rather than after.
| What happened | Homeowners policy | Flood policy |
|---|---|---|
| Water from a bayou, street or yard rises and comes inside | Not covered | Covered |
| Storm surge pushes water into the house | Not covered | Covered |
| Wind damages the roof and rain gets in | Usually covered, after the wind and hail deductible | Not covered |
| A pipe bursts inside the house | Usually covered | Not covered |
| A sewer or drain backs up | Often only with an optional water-backup add-on | Only when flooding directly causes it |
A general guide, not policy wording. Your own policy decides, and Ricardo can read it with you.
What a flood policy covers
Building, belongings, or both.
Federal flood insurance comes in two parts, each with its own limit and its own deductible. Homeowners usually want both. Renters only need the second.
-
Building
Up to $250,000
The structure itself
Foundation, walls and floors, electrical and plumbing, furnace and water heater, built-in appliances, and permanently installed carpet and cabinets.
-
Contents
Up to $100,000
What you own inside
Furniture, clothing, electronics, and portable appliances like a washer and dryer. It's bought separately, so it's easy to go without it by accident.
-
Above the limits
Excess or private flood
When rebuilding costs more
If your house would cost more than $250,000 to rebuild, private or excess flood coverage can sit on top of the federal policy. Ricardo can show where the gap starts.
Check your ZIP code
See your ZIP code's flood-claim record.
A flood zone tells you how a property is priced, not how often its neighborhood has actually flooded. Enter a Harris County ZIP code to see FEMA's claim record for it.
FEMA OpenFEMA NFIP claims, all loss years on record, 136 Harris County ZIP codes with at least 25 paid claims. Open the full ZIP lookup
Free flood tools
Answer your next flood question yourself.
Each tool is free, works without an account, and ends with a way to reach the office if you'd rather talk it through.
How risky is my address?
How much coverage do I need?
Start where you are
Four reasons Houston households call about flood.
-
Buying or refinancing
Your lender says flood insurance is required.
Send the lender's letter and your closing date. A flood policy bought with the loan has no 30-day wait, so timing it to the closing matters.
Text the lender letter -
Outside the high-risk zone
Your flood map says Zone X.
Zone X means moderate to low risk, not no risk, and lenders usually won't require a policy there. Ask what coverage would cost at your address before you decide to skip it.
Call about your address -
Renting
You rent and your things aren't covered.
Renters insurance excludes flood. A contents-only flood policy protects what you own, up to $100,000, whatever floor you live on.
Text your rental address -
Already insured
You have flood, but haven't checked the limits.
Building and contents limits, deductibles and the renewal date are worth a second look, especially after a renovation or a jump in rebuild costs.
Call for a limits check
How it works
From your address to a decision in three steps.
-
Send your address
Call, or text the property address. Add the lender letter or your current policy if you have them; a phone photo is fine.
-
Review it together
Ricardo goes through the zone and claim history, what your lender requires, building and contents options, deductibles, and the date coverage would start.
-
Decide
If you go ahead, coverage starts after the waiting period, or at closing when it's bought with your mortgage. If you'd rather think it over, that's fine too.
Helpful to have nearby
- The property address, and whether you own or rent it
- Your lender or escrow letter and closing date, if you're buying
- Your current flood or homeowners declarations page
- An elevation certificate, if you already have one (not needed to start)
Why Ricardo
One local agent for flood, home and auto.
-
Explained before you buy
Ricardo walks through what a flood policy pays for, and what it doesn't, before you decide.
-
Next to your home and auto
Flood, homeowners and auto questions can be handled in one conversation, by one office that sees the whole picture.
-
English or Spanish
Lender letters and policy pages are read in whatever language they arrived in, and explained in the one you prefer.
-
An office you can visit
1235 North Loop W, inside the Telemundo building off 610. Most reviews happen by phone or text.
Questions
Flood insurance questions Houston households ask first.
Updated .
Does homeowners insurance cover flooding in Houston?
No. Standard homeowners and renters policies exclude flood damage, including rising water from storms, bayous and storm surge. Flood coverage is a separate policy with its own limits and deductibles.
How long does it take for flood insurance to start?
A new federal flood policy usually takes effect 30 days after purchase. There's no wait when it's bought while making, increasing, extending or renewing a mortgage, and a one-day wait when a map update newly places the property in a high-risk zone and you buy within 12 months.
Do I need flood insurance if I'm not in a flood zone?
Lenders usually don't require it outside the high-risk zone, but that isn't the same as being safe. More than half of the homes Hurricane Harvey flooded were outside designated flood zones, and in our analysis of 170,843 Harris County claims, 47.6% of flood-claim dollars went to properties outside the high-risk zone.
How much flood insurance can I buy?
The National Flood Insurance Program covers up to $250,000 for a home's structure and up to $100,000 for its contents, bought separately. If rebuilding would cost more, private or excess flood coverage can be added on top.
Can renters get flood insurance in Houston?
Yes. Renters can buy flood coverage for their belongings, up to $100,000 through the National Flood Insurance Program. A standard renters policy excludes flood damage.
Can I review flood together with my home and auto insurance?
Yes. The Houston office can go through home, auto and flood in one conversation, so each policy is sized on its own and nothing falls between them.
Can the flood insurance review be in Spanish?
Yes. Ricardo and the Houston office handle the whole review in Spanish or English, including documents from your lender.
Before you need it
Get your Houston address reviewed for flood.
Call, or text the address. Ricardo's office will tell you what flood coverage would cost at that address, what it would pay for, and the date it would start.
Barcelo & Associates Insurance
1235 North Loop W, Ste 1010Houston, TX 77008
Inside the Telemundo Building, North Loop West
- Mon–Thu
- 9 AM–6 PM
- Friday
- 9 AM–5 PM
Rather type than call? Request a quote here.
Two short steps. The Houston office replies during office hours, however you prefer. If it's urgent, a call is still the fastest way.
A licensed agent reviews every request. This form does not quote prices or confirm coverage.
Where these facts come from.
Every point here can be checked at the original source. Links confirmed .
- Buy a Flood Insurance Policy FloodSmart (FEMA)
How NFIP policies are purchased, what building and contents coverage include, and the standard waiting period before coverage takes effect.
- Flood Insurance Texas Department of Insurance
Texas-specific consumer guidance on flood coverage, including that standard homeowners and renters policies exclude flood.
- What Is My Flood Risk? FloodSmart (FEMA)
Flood-zone risk categories, and FEMA's own finding that from 2014 to 2024 nearly one-third (29%) of NFIP claims came from outside high-risk areas.
- OpenFEMA Dataset: NFIP Claims (v3) FEMA
The claim-level dataset behind this site's Harris County flood-claim analysis.
Important coverage notes
- This page is educational. It does not replace a policy, a quote, or a licensed coverage review.
- Product names and availability may vary by company and underwriting requirements.
- Coverage is based on selections made and is subject to terms, conditions, availability, and qualifications.
- Text messaging frequency may vary. Message and data rates may apply. Consent to receive texts is not a condition of purchase.