Homeowners insurance · Houston
Houston homeowners insurance, reviewed line by line by a local agent.
Renewal went up, a closing date is coming, or the roof is getting older? Ricardo Barcelo reads your policy with you (dwelling limit, wind and hail deductible, roof coverage and liability), then quotes home and auto together when that helps.
Rather type? Request a home quote
- 4.9 on Google, 265 reviews
- No charge to review your coverage
- English or Spanish · hablamos español
- Mon–Thu 9–6, Fri 9–5
Already a customer with a claim or billing question? Go to customer service.
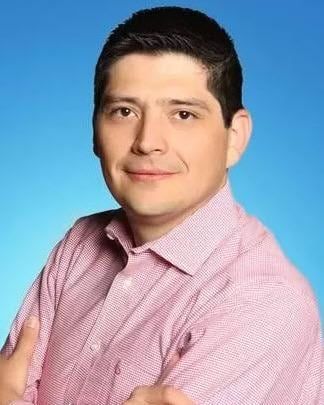
Ricardo Barcelo
Allstate exclusive agent, Barcelo & Associates Insurance, Houston Heights
Key facts
-
1% to 5%
is the usual range for a Texas wind and hail deductible, figured as a percentage of your dwelling coverage. 2% of $300,000 is $6,000.
Source: Storm deductible calculator
-
80%
of replacement cost is the least most insurers will let you insure your house for. Some require 100%.
-
Not included
Flood isn't covered by a standard homeowners policy. It's a separate policy, and it usually waits 30 days to start.
Source: Flood insurance in Houston
Your declarations page
Four lines that decide what a claim pays.
The declarations page is the summary sheet at the front of your policy. Most of what matters in a Houston claim comes down to these four lines, and Ricardo goes through each one with you.
-
Dwelling coverage (Coverage A)
What it would cost to rebuild your house. That's different from what you paid for it or what it would sell for.
Check: Is the limit close to today's rebuild cost, including any renovations?
-
Wind and hail deductible
Usually a percentage of Coverage A, not a flat amount. It's what you pay first on a hail or windstorm claim.
Check: What is that percentage in dollars, and could you pay it after a storm?
-
Roof coverage
Replacement cost pays for a new roof at today's prices. Actual cash value subtracts for age, so an older roof can pay far less.
Check: Does your policy pay replacement cost or actual cash value on the roof?
-
Liability and loss of use
Liability covers injury or damage you're responsible for. Loss of use pays for somewhere to live while the house is repaired.
Check: Are both high enough for your household and a long repair?
Texas Department of Insurance, Home insurance guide: replacement cost “would pay for a new roof at today's prices.”
Try the numbers
What would your wind and hail deductible cost you?
Enter the dwelling coverage from your declarations page and pick your deductible. Nothing is saved or sent.
You'd pay the first $6,000 of a covered wind or hail claim.
| Deductible | You pay first |
|---|---|
| 1% | $3,000 |
| 2% | $6,000 |
| 3% | $9,000 |
| 5% | $15,000 |
A lower percentage usually means a higher premium; this does not estimate premiums. Open the full storm deductible calculator
Ricardo can check this against your own declarations page.
Read the exclusions
What a standard home policy usually leaves out.
Exclusions are where most claim surprises come from. These are the common ones in Texas, and what you can do about each.
| Usually excluded | What it means | What you can do |
|---|---|---|
| Flood | Rising water from storms, bayous or surge isn't covered. | Buy a separate flood policy, ideally more than 30 days before you need it. |
| Wear and tear | Damage from age or missed maintenance, like a roof that simply wore out. | Know your roof's age and keep up with repairs. |
| Earth movement | Earthquakes and ground movement. | Ask whether coverage for foundation or slab damage can be added. |
| Mold | Mold removal, unless it comes from a covered loss. | Fix leaks quickly and report covered water damage right away. |
Your policy's exclusions section is the final word. Ricardo can read it with you. Get flood insurance reviewed
Home and auto together
A house and two cars? Review them in one conversation.
Bundling home and auto can qualify for a multi-policy discount. Ricardo compares the total for both policies and the coverage behind each, so a discount never hides a thinner home policy.
- One review for the house and every vehicle
- The total cost compared, not just one bill
- Coverage checked line by line on both
Start where you are
What usually brings Houston homeowners in.
-
Closing on a home
Your lender needs proof of insurance.
Send the property address, closing date and the lender's requirements. Ricardo works out the coverage and the paperwork your lender asks for.
Text your closing details -
Renewal
Your renewal went up and you don't know why.
Text a photo of the renewal. Ricardo compares it with last year's policy: limits, deductibles, and what actually changed.
Text your renewal -
Older roof
Your roof is getting older, or has had a claim.
Roof age can change how a roof claim is paid. Find out whether yours is replacement cost or actual cash value before the next hail storm.
Call about your roof -
Comparing companies
You want to see how your current policy stacks up.
Bring your declarations page so a quote matches your current coverage line for line, instead of comparing two prices for two different policies.
Call to compare
How it works
From your policy to a clear answer in three steps.
-
Send what you have
Call, or text a photo of your declarations page or renewal. Buying? Send the address and closing date.
-
Review it together
Ricardo walks through the dwelling limit, deductibles, roof coverage, liability and anything your lender needs, then quotes home and auto together if it makes sense.
-
Decide
Choose your coverage with the numbers in front of you. If you're buying, the office sends your lender what it needs before closing.
Helpful to have nearby
- The property address, year built and rough square footage
- Your current declarations page or renewal notice
- Roof age and any updates to the roof, plumbing, wiring or HVAC
- Your closing date and lender details, if you're buying
- Your vehicles and drivers, if you'd like home and auto reviewed together
Why Ricardo
One local agent for your home, your cars and your flood coverage.
-
Your policy, line by line
Ricardo explains each line of the policy himself, so you know what a claim would pay before you need one.
-
Home and auto in one place
One office for the house and every vehicle, with the total compared rather than one bill at a time.
-
English or Spanish
Lender requests, escrow notices and policy terms explained in whichever language you prefer.
-
An office you can visit
1235 North Loop W, inside the Telemundo building off 610. Most reviews happen by phone or text.
Questions
Homeowners insurance questions Houston owners ask first.
Updated .
How much homeowners insurance do I need in Houston?
Enough dwelling coverage to rebuild the house at today's costs, which is different from its market value. Most insurers require you to insure at least 80% of replacement cost, and some require 100%. Ricardo can check the figure on your declarations page with you.
What is a wind and hail deductible?
In Texas it's usually a percentage of your dwelling coverage, often 1%, 2%, 3% or 5%. On $300,000 of dwelling coverage, a 2% deductible means you pay the first $6,000 of a covered wind or hail claim.
Does homeowners insurance cover flooding?
No. Flood damage is excluded from standard homeowners policies. Flood coverage is a separate policy, and a new one usually takes 30 days to start.
Does my roof's age affect my coverage?
It can. Some policies pay roof claims at actual cash value, which subtracts for age, instead of replacement cost. It's worth checking which one yours uses before storm season.
Can you help when my lender needs proof of insurance before closing?
Yes. Send the property address, closing date and the lender's requirements, and the office will work through the coverage and the paperwork your lender asks for.
Will bundling home and auto lower my price?
It can qualify for a multi-policy discount, but there's no guarantee. Price depends on the home, vehicles, drivers and coverage you choose. Ricardo compares the total so you can decide.
Can homeowners get help in Spanish?
Yes. Buyers and homeowners can go through lender requests, escrow notices and policy terms in Spanish, with documents read in whichever language they arrived in.
Ready when you are
Get your home policy reviewed by someone who explains it.
Call, or text a photo of your declarations page or renewal. Ricardo's Houston office will go through what you have, what's missing, and what a home and auto quote would look like.
Barcelo & Associates Insurance
1235 North Loop W, Ste 1010Houston, TX 77008
Inside the Telemundo Building, North Loop West
- Mon–Thu
- 9 AM–6 PM
- Friday
- 9 AM–5 PM
Rather type than call? Request a quote here.
Two short steps. The Houston office replies during office hours, however you prefer. If it's urgent, a call is still the fastest way.
A licensed agent reviews every request. This form does not quote prices or confirm coverage.
Where these facts come from.
Every point here can be checked at the original source. Links confirmed .
- Home insurance guide Texas Department of Insurance
What standard Texas homeowners policies usually exclude (flood, earth movement, wear and tear, most mold), replacement cost versus actual cash value for a roof, and insuring a house for at least 80% of its replacement cost.
- Flood Insurance Texas Department of Insurance
Texas-specific consumer guidance on flood coverage, including that standard homeowners and renters policies exclude flood.
Important coverage notes
- This page is educational. It does not replace a policy, a quote, or a licensed coverage review.
- Product names and availability may vary by company and underwriting requirements.
- Coverage is based on selections made and is subject to terms, conditions, availability, and qualifications.
- Text messaging frequency may vary. Message and data rates may apply. Consent to receive texts is not a condition of purchase.